Summary
- Mahindra & Mahindra Financial Services reported standalone profit after tax of ₹882 crore for Q2 FY27, up 55% from ₹569 crore a year earlier.
- Quarterly loan disbursements increased 22% to ₹16,499 crore.
- Business assets under management (AUM) reached ₹1,46,512 crore, growing 15% year-on-year.
- Total standalone income rose 15% to ₹5,175 crore.
- Net interest margin remained at 7%, while credit costs declined to 1.6% from 2.2%.
- Stage 3 assets improved to 3.4% from 3.9%, and Stage 2 assets fell to 4.7% from 5.8%.
- Consolidated profit was ₹911 crore, up 61%, and should not be confused with the ₹882-crore standalone figure.
- Lending outside the vehicle-finance business recorded 52% growth in disbursements.
Mahindra Finance Announces Strong Q2 FY27 Results
Mahindra & Mahindra Financial Services Limited, commonly known as Mahindra Finance, reported a strong improvement in its financial performance for the quarter ended 30 September 2026.
The non-banking financial company announced its unaudited results on Wednesday, 21 October 2026, making the earnings report an important development for the following morning’s financial-news coverage.
Standalone profit after tax rose 55% year-on-year to ₹882 crore, compared with ₹569 crore in the corresponding quarter of FY26.
Loan disbursements increased 22% to ₹16,499 crore, while business assets under management grew 15% to ₹1.47 lakh crore.
The results reflect stronger lending activity and lower credit costs.
However, investors should assess the sustainability of these improvements before drawing conclusions about future earnings or share-price performance.
Mahindra Finance Q2 FY27 Financial Highlights
| Standalone metric | Q2 FY27 | Q2 FY26 | YoY change |
|---|---|---|---|
| Profit after tax | ₹882 crore | ₹569 crore | +55% |
| Total income | ₹5,175 crore | ₹4,489 crore | +15% |
| Loan disbursements | ₹16,499 crore | ₹13,514 crore | +22% |
| Business AUM | ₹1,46,512 crore | ₹1,27,246 crore | +15% |
| Pre-provision operating profit | ₹1,791 crore | ₹1,499 crore | +20% |
| Credit costs | ₹630 crore | ₹751 crore | −16% |
| Net interest margin | 7.0% | 7.0% | Unchanged |
| Return on assets | 2.2% | 1.6% | Improved |
Source: Mahindra Finance’s official Q2 FY27 earnings release dated 21 October 2026. Figures are rounded as disclosed by the company.
These results demonstrate that the company’s profit grew substantially faster than total income.
One important reason was the reduction in credit costs, which decreased by ₹121 crore compared with the previous year.
Why Did Mahindra Finance Profit Increase 55%?
Mahindra Finance’s reported improvement in standalone profit was supported by three major developments.
1. Higher Loan Disbursements
The company disbursed ₹16,499 crore of loans during the September quarter.
This was 22% higher than the ₹13,514 crore disbursed a year earlier.
Higher disbursements can expand future interest-earning assets, provided the loans remain outstanding and borrowers meet their repayment commitments.
However, higher disbursements do not automatically translate into equivalent growth in interest income during the same quarter.
The timing of loan origination, repayment schedules and yields also matter.
2. Lower Credit Costs
Mahindra Finance reported credit costs of ₹630 crore, compared with ₹751 crore in Q2 FY26.
As a percentage of average assets, credit costs fell to 1.6% from 2.2%.
This reduction helped profitability.
For a lending business, credit costs are an important expense because they reflect provisions and recognised losses associated with the loan portfolio.
A sustained reduction can improve earnings, but it must be evaluated alongside the quality of the underlying loans.
3. Improved Operating Profit
Pre-provision operating profit increased 20% to ₹1,791 crore.
This measures operating profitability before accounting for credit provisions and certain other items.
The increase indicates stronger underlying business performance.
Nevertheless, pre-provision operating profit is not the same as final profit available to shareholders.
Loan Book Grows to ₹1.46 Lakh Crore
Mahindra Finance reported business AUM of ₹1,46,512 crore at the end of September 2026.
This compares with ₹1,27,246 crore a year earlier.
The 15% growth reflects continued demand for its lending products.
The company is known for vehicle and tractor financing, particularly in rural and semi-urban India.
It also offers financing across passenger vehicles, commercial vehicles, used vehicles, small businesses and other categories.
AUM represents the value of assets managed under the company’s relevant business definition.
It should not be confused with quarterly disbursements.
Disbursements measure the loans issued during a particular period, whereas AUM reflects the outstanding managed portfolio at a point in time.
Asset Quality Improves: Stage 3 Assets Fall
Asset quality is one of the most important indicators for banks and non-banking financial companies.
Mahindra Finance reported an improvement in its Stage 2 and Stage 3 asset classifications.
| Asset-quality indicator | Q2 FY26 | Q2 FY27 |
|---|---|---|
| Stage 2 assets | 5.8% | 4.7% |
| Stage 3 assets | 3.9% | 3.4% |
| Collection efficiency | 96% | 97% |
Stage 2 assets generally represent loans that have experienced a significant increase in credit risk.
Stage 3 assets generally represent credit-impaired loans.
The decline in both ratios indicates an improvement in the company’s reported loan-quality profile.
Collection efficiency also increased to 97%.
Read Also: Gold Loan Risks Rise in India: Bajaj Finance and Piramal Flag Early Repayment Stress
However, investors should continue monitoring overdue loans and repayment behaviour in future quarters.
An improvement in one period does not eliminate the possibility of future loan losses.
More Stories

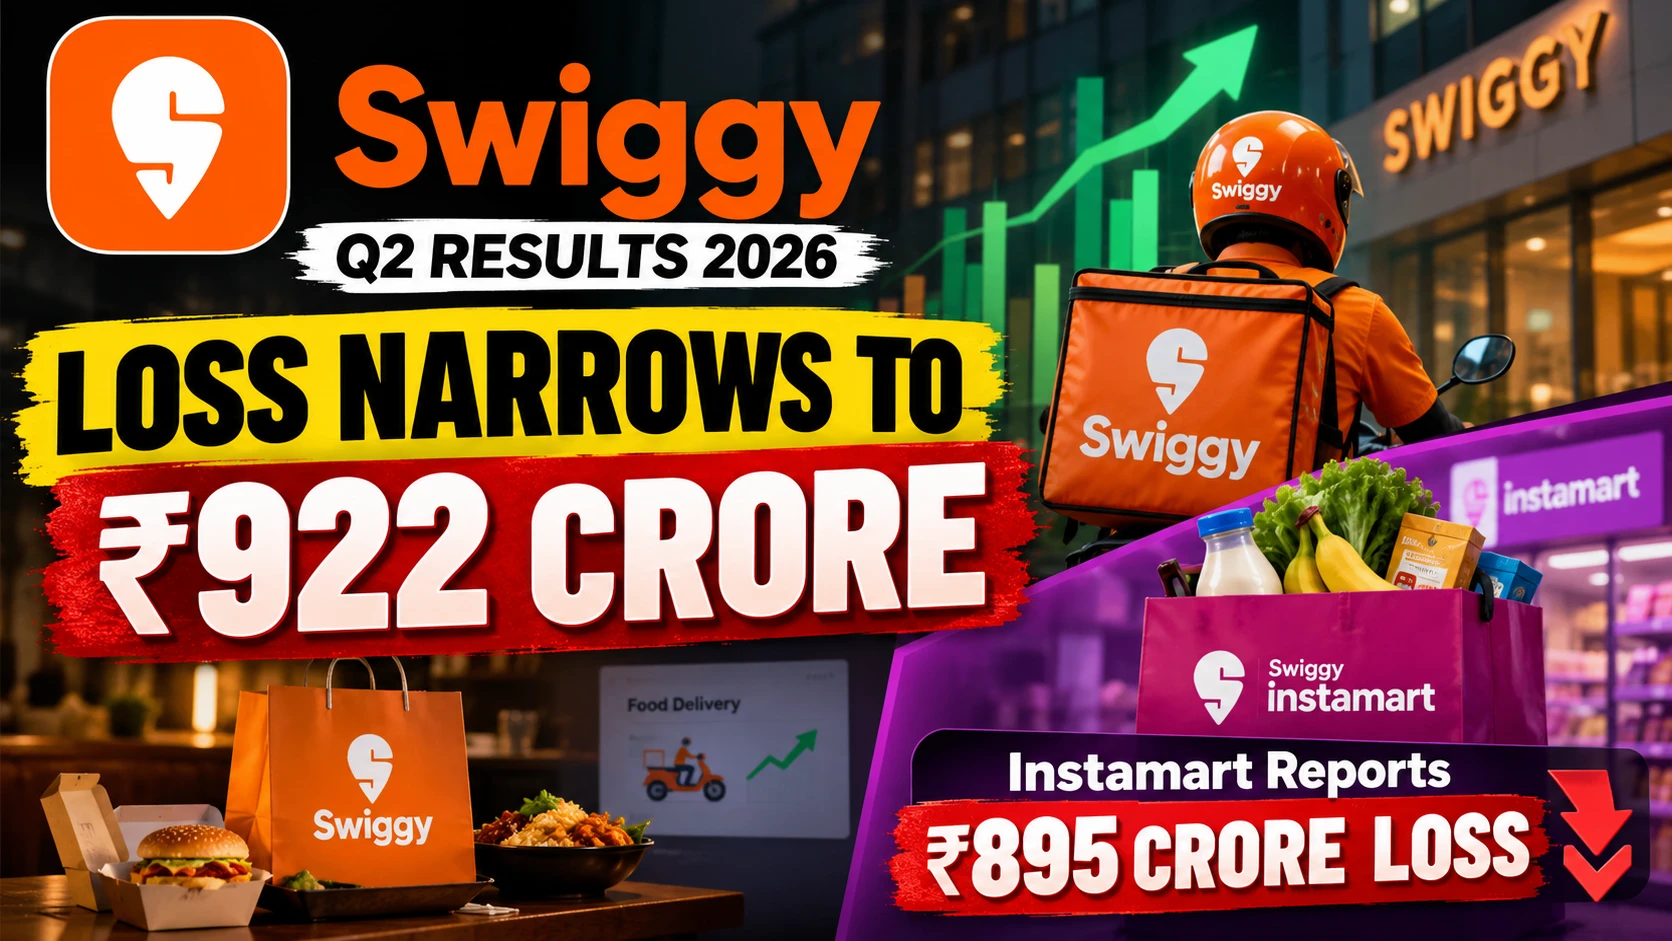
Swiggy Q2 Results 2026: Net Loss Narrows to ₹922 Crore, Instamart Loss at ₹895 Crore

RBI Rejects All 224 Treasury Bill Bids in ₹23,000 Crore Auction: Why It Matters for Investors
Persistent Systems Opens ₹4,265 Crore QIP: Floor Price Clarified at ₹5,761, What Investors Should Know
Mahindra Finance Q2 Results 2026: Profit Jumps 55% to ₹882 Crore, Loan Disbursements Rise 22%
Net Interest Margin Remains at 7%
Mahindra Finance reported a net interest margin of 7.0%, unchanged from the previous year’s corresponding quarter.
The net interest margin provides insight into lending profitability relative to the applicable asset base under the company’s reporting definition.
An unchanged margin suggests that the company maintained this important measure despite changing financial conditions.
However, margins can be affected by borrowing costs, loan yields, product mix and competitive pricing.
The company’s future profitability will partly depend on whether it can maintain margins while continuing to expand lending.
Non-Vehicle Lending Grows 52%
One of the more notable developments was the expansion of lending beyond the company’s traditional vehicle-finance business.
Mahindra Finance reported 52% year-on-year growth in non-vehicle-finance disbursements.
This category includes SME lending, personal loans and other businesses, including Mahindra Rural Housing Finance.
Diversification can reduce dependence on any single lending segment.
For example, a lender heavily concentrated in commercial vehicles may be vulnerable to a downturn in that sector.
Expanding into SME or personal lending can provide additional growth opportunities.
However, each lending category carries different credit risks, customer-acquisition costs and operating requirements.
Growth in new businesses should therefore be assessed alongside their profitability and asset quality.
Vehicle and Tractor Finance Remain Important
Despite diversification, vehicle and tractor finance remain central to Mahindra Finance’s business.
The company continues to serve customers seeking financing for agricultural equipment, passenger vehicles, used vehicles and light commercial vehicles.
These products are particularly relevant to customers in rural and semi-urban markets.
Demand can be influenced by agricultural income, vehicle sales, interest rates, rural economic conditions and seasonal patterns.
The company stated that its Udaan transformation programme is now embedded across vehicle lending and collections.
Its strategy includes improvements in operating processes and the use of digital technology.
Consolidated Profit Rises 61% to ₹911 Crore
Mahindra Finance also reported consolidated financial results.
On a consolidated basis, profit after tax reached ₹911 crore, compared with ₹566 crore a year earlier.
This represents approximately 61% growth.
Consolidated total income increased 18% to ₹5,962 crore.
Total consolidated assets rose 21% to ₹1,80,292 crore.
| Consolidated metric | Q2 FY27 | Q2 FY26 |
|---|---|---|
| Total income | ₹5,962 crore | ₹5,049 crore |
| Profit after tax | ₹911 crore | ₹566 crore |
| Total assets | ₹1,80,292 crore | — |
Standalone results describe the reporting company, whereas consolidated results include the relevant subsidiaries and other entities as required by accounting standards.
Investors should not mix the ₹882-crore standalone profit with the ₹911-crore consolidated profit when making year-on-year comparisons.
Capital Adequacy and Liquidity Position
Mahindra Finance reported a capital adequacy ratio of 18.0%.
Its Tier 1 capital ratio stood at 16.2%.
Capital adequacy helps indicate the financial resources available to absorb certain risks.
The company also reported a liquidity buffer exceeding ₹16,150 crore.
Provision coverage on gross Stage 3 assets was 56.6%.
These indicators provide additional context beyond quarterly profit growth.
However, investors should assess them against applicable regulatory requirements, funding maturity profiles and future business needs.
What Did Management Say?
Mahindra Finance Managing Director and CEO Raul Rebello said the company’s operational changes were producing stronger and more consistent outcomes.
Management highlighted growth in disbursements, lower credit costs and the company’s long-term FY31 ambitions.
The message indicates a continued focus on disciplined expansion, rather than loan-book growth alone.
However, management targets are forward-looking statements.
They should not be treated as guaranteed financial outcomes.
Read Also: RBI MPC Minutes October 2026: More Repo Rate Hikes Possible, but Two Members Warn of Growth Risks
What Could the Results Mean for Mahindra Finance Shares?
The Q2 results provide several encouraging indicators for investors.
Profitability improved, loan disbursements expanded, and reported credit-risk indicators declined.
Nevertheless, share prices are influenced by valuation, market expectations, interest rates and broader stock-market conditions.
A company can report strong earnings and still experience share-price volatility.
Because this article is prepared before the 22 October market session, it does not claim that Mahindra Finance shares have already risen or fallen in response to the results.
Any intraday or closing-price update should be added only after checking official NSE or BSE data.
Key Risks Investors Should Monitor
Funding Costs
Mahindra Finance borrows funds to support lending operations.
Higher market interest rates can affect its cost of funding.
Credit Quality
Even with improving Stage 2 and Stage 3 indicators, future repayment conditions remain important.
Rural and Vehicle Demand
Demand for tractors, passenger vehicles and commercial vehicles can change with economic and industry conditions.
Rapid Loan Growth
Faster disbursement growth must be supported by adequate underwriting and collections.
Valuation
Strong quarterly results do not automatically mean that a stock is attractively valued.
Investors should compare earnings sustainability, growth prospects and the current market price.
Conclusion
Mahindra Finance delivered a strong Q2 FY27 performance, reporting 55% growth in standalone profit to ₹882 crore and a 22% increase in loan disbursements.
Its AUM expanded to ₹1.46 lakh crore, while lower credit costs and improved asset-quality indicators supported profitability.
Consolidated profit increased 61% to ₹911 crore.
The key takeaway is that Mahindra Finance’s earnings improvement reflects both business expansion and better credit costs. Investors should monitor whether these trends remain sustainable in subsequent quarters.
Official and Supporting Sources
- Mahindra Finance — Q2 FY27 Official Earnings Release
- Mahindra Finance — Regulatory Filings
- Business Standard — Q2 Profit, Loan Growth and Credit Costs
Disclaimer: This article was prepared with AI assistance using the company’s official stock-exchange disclosure and financial reporting. It is for general information and education, not investment, tax, legal or financial advice. Financial results, company projections and market prices may change. EduTaxTuber disclaims liability for losses to the extent permitted under applicable Indian law.
Disclaimer: EduTaxTuber provides content for general educational and informational purposes only. While we make reasonable efforts to keep the information accurate and updated, laws, regulations, market conditions, software features, and other information may change. Some content may be created or assisted by AI tools and may contain errors or omissions. Readers should verify important information with official sources or qualified professionals before making any tax, legal, financial, investment, business, or other decisions. EduTaxTuber does not guarantee the completeness or accuracy of the information and does not provide professional advice.
