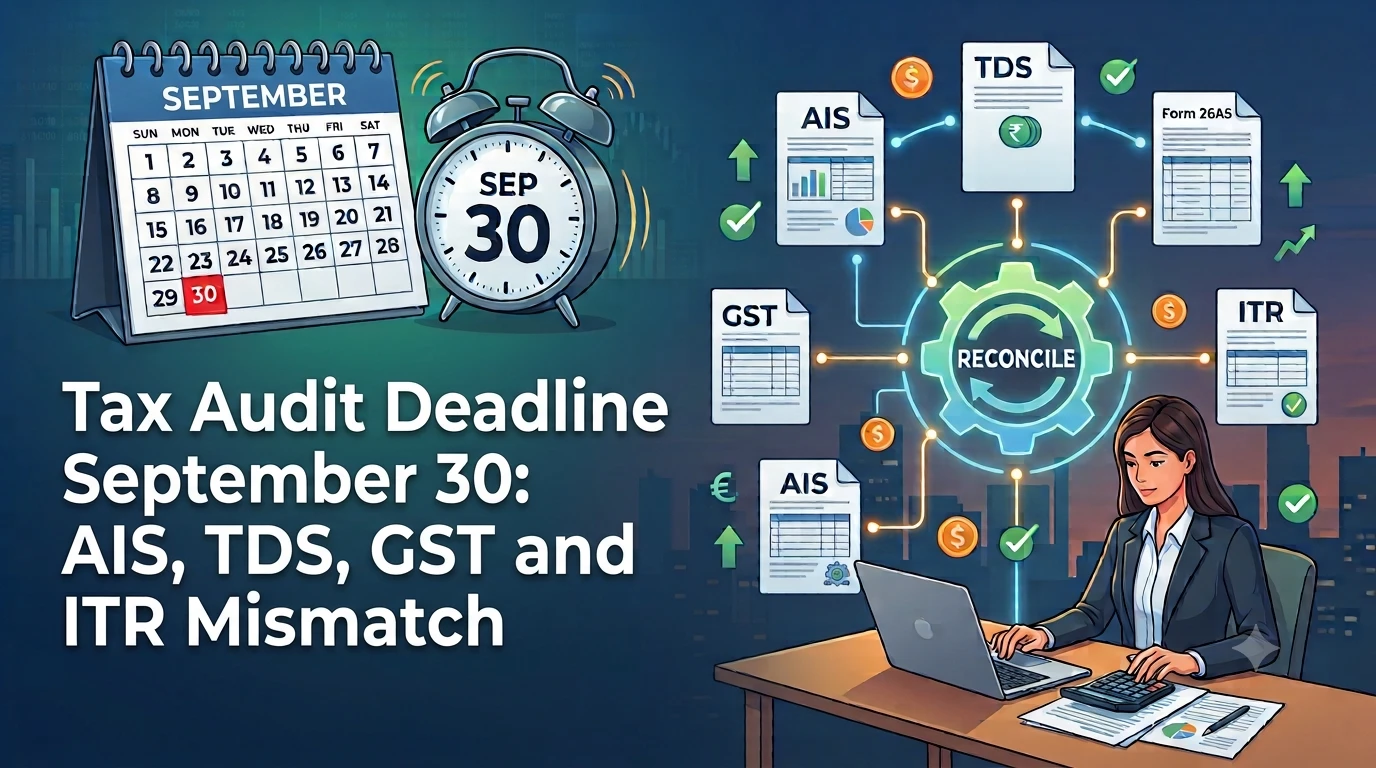
Tax Audit Deadline September 30: Why AIS, TDS and GST Figures May Not Match Your ITR
Summary
- September 30, 2026 is the tax-audit report deadline for applicable taxpayers for AY 2026-27.
- GST turnover, books of account and ITR figures may differ because of timing differences, credit/debit notes, advances, exempt supplies and accounting treatment.
- AIS and TIS may contain transactions that require verification and not every entry appearing in AIS automatically means taxable income.
- TDS/TCS mismatches can affect the tax credit available in the ITR, particularly where the deductor reports an incorrect PAN, amount or transaction.
Tax Audit Deadline September 30, 2026: What Taxpayers Need to Check
The September 30 tax audit deadline is approaching, and taxpayers whose accounts are subject to tax audit should not leave reconciliation work until the final few days.
For FY 2025-26 relevant to AY 2026-27, the Income Tax Department has confirmed that the tax audit report is due on 30 September 2026. For this year, the applicable tax audit forms continue to be Form 3CA/3CB and Form 3CD under the Income-tax Act, 1961.
However, completing the audit report is not simply a matter of uploading a form.
A taxpayer’s books of account, financial statements, GST returns, Annual Information Statement (AIS), Taxpayer Information Summary (TIS), Form 26AS, TDS certificates and ITR may contain different figures. These differences do not automatically mean that there is an error or undisclosed income.
The important question is:
Why is there a difference, and can the taxpayer explain and support it with proper records?
That is why reconciliation should be completed before the tax audit report and ITR are finalised.
Why Can Books, GST, AIS, TIS and ITR Figures Be Different?
Many taxpayers assume that the turnover or income appearing in every government system should be exactly the same.
In practice, this is not always the case.
Different statements are prepared for different purposes and may follow different reporting mechanisms. For example, GST returns report supplies under GST law, while the books of account are maintained according to the taxpayer’s accounting system.
Similarly, AIS contains information reported by various reporting entities. Form 26AS primarily provides tax-credit-related information along with other specified information.
Therefore, a mismatch should be treated as a reconciliation issue, not automatically as an indication of tax evasion or incorrect reporting.
Common reasons include:
- Timing differences
- Duplicate reporting
- Incorrect PAN reporting
- Wrong amount reported by a deductor or reporting entity
- Credit notes or debit notes
- Advances and their subsequent adjustment
- Accounting treatment differences
- Exempt or non-GST transactions
- Transactions reported in a different financial period
- TDS/TCS statements filed or corrected later
- Differences between gross receipts and taxable turnover
The objective is to identify the reason, retain supporting documents and report the correct figure under the applicable tax law.
GST Turnover May Not Match Turnover in Your ITR
One of the most important reconciliations before a tax audit is:
Books of account vs GST returns vs ITR
GST Form GSTR-1 contains details of outward supplies, including invoice-level information, credit and debit notes, exports, advances, amendments and other categories of outward supplies.
Because GST reporting and income-tax accounting serve different purposes, the turnover shown in GST returns may not always be identical to the revenue figure appearing in the books or ITR.
Read Also: Missed 31 August ITR Deadline? Know Your Options Now
For example, differences may arise because of:
1. Credit and debit notes
A credit note or debit note can change the reported value of supplies and may affect the reconciliation between books and GST returns.
2. Advances
Advances can create timing differences depending on the nature of the transaction and the applicable GST and accounting treatment.
3. Exempt and non-GST supplies
Not every receipt appearing in the books necessarily forms part of taxable GST turnover.
4. Accounting-period differences
An invoice, supply or receipt may be recorded differently for accounting and GST reporting purposes depending on the circumstances.
5. Amendments in GST returns
A transaction may have originally been reported incorrectly and subsequently amended.
Therefore, if GST turnover and book turnover do not match, the taxpayer should prepare a GST reconciliation statement explaining the difference.
Suggested reconciliation: Tax Audit Deadline September 30
A practical reconciliation can contain:
Turnover as per books
± GST-related adjustments
± Credit/debit notes
± Advances
± Exempt/non-GST items
± Timing differences
= Turnover reported in GST returns
The exact reconciliation depends on the nature of the business and the applicable accounting and GST treatment.
AIS and TIS: Does Every Transaction Shown There Become Taxable Income?
This is one of the most common areas of confusion during ITR filing.
The Annual Information Statement (AIS) and Taxpayer Information Summary (TIS) provide taxpayers with information reported by various entities to the Income Tax Department.
Such information can include items relating to:
- Interest income
- Dividend income
- Securities transactions
- Professional receipts
- Business receipts
- TDS/TCS
- Certain financial transactions
- Other information reported by financial institutions and other reporting entities
However, taxpayers should not simply copy every AIS entry into the ITR without understanding the underlying transaction.
An AIS entry should be compared with:
- Books of account
- Bank statements
- Form 26AS
- TDS certificates
- Investment statements
- Demat statements
- Invoices
- Contracts and agreements
- Other source documents
For example, suppose a transaction appears in AIS but the taxpayer does not recognise it as income.
The first step should be to identify what the transaction actually represents.
It could be:
- A duplicate entry
- A transaction belonging to another financial year
- A transaction reported incorrectly
- A gross amount where only a portion is taxable
- A transaction already recorded under another head
- A transaction with a different accounting treatment
The taxpayer should establish the correct nature of the transaction before filing the return.
What to Do If AIS Shows Incorrect Information?
If information appearing in AIS is incorrect, the taxpayer should not ignore it.
The Income Tax Department provides mechanisms through the AIS portal for taxpayers to provide appropriate feedback on information displayed in AIS.
Where the error originates with the reporting entity, the taxpayer may also need to approach that entity for correction.
For example, if a bank, broker, employer or another reporting entity has reported incorrect information, the taxpayer should maintain evidence supporting the correct position and seek correction where appropriate.
This is particularly important where the incorrect information could affect taxable income, TDS/TCS credit or other disclosures.
TDS Mismatch: Why Form 26AS Should Be Checked Before Filing ITR
A TDS mismatch can directly affect the amount of tax credit available to the taxpayer.
Taxpayers should reconcile:
Books/Income records → TDS certificates → Form 26AS → AIS → ITR
The Income Tax Department’s tax-credit mismatch guidance specifically covers mismatches involving TDS, TCS and tax payments.
Common reasons for TDS mismatch include:
- Incorrect PAN reported by the deductor
- Incorrect TDS amount
- Wrong assessment year
- Deductor failing to file the TDS statement
- Delayed filing of the TDS statement
- TDS statement containing an error
- Correction statement not yet processed
- Difference between the taxpayer’s records and the tax statement
More Stories

ixigo Q2 Results: Profit Reaches ₹63.42 Crore, Revenue Rises 13% as Hotels Business Expands
FPI Outflows October 2026: Foreign Investors Withdraw ₹52,100 Crore From Indian Stocks

Paras Healthcare IPO 2026: ₹1,450 Crore Issue, Price Band, Dates and Review
57th GST Council Meeting 2026: Major Reforms Proposed for Taxpayers and Businesses
Example of a TDS mismatch: Tax Audit Deadline September 30
Suppose a client pays a professional ₹5 lakh and deducts ₹50,000 as TDS.
The taxpayer has the TDS certificate showing ₹50,000.
However, the amount does not appear correctly in Form 26AS.
The taxpayer should not simply assume that the credit will automatically become available.
The deductor may need to correct the TDS statement.
The Income Tax Department states that where a TDS mismatch exists, the taxpayer should inform the employer or deductor, who may need to file a revised TDS statement.
The department also provides a Tax Credit Mismatch service through the e-Filing portal to identify differences between tax credits reported in the ITR and those reflected in Form 26AS.
What Happens If TDS Is Deducted but Not Showing in Form 26AS?
This situation requires particular attention.
A taxpayer may have proof that TDS was deducted but may not find the corresponding credit in Form 26AS.
The taxpayer should:
- Check the TDS certificate.
- Verify the PAN mentioned in the certificate.
- Check the amount of TDS.
- Compare the financial year and relevant details.
- Contact the deductor.
- Ask the deductor to correct the TDS statement, if necessary.
- Recheck Form 26AS after correction.
- Reconcile the final tax credit before filing or finalising the return.
The Income Tax Department’s guidance notes that tax credit claimed in the ITR is restricted to the amount reflected in Form 26AS.
Therefore, unresolved TDS mismatches should not be treated as a minor bookkeeping issue.
Tax Audit Report and ITR Must Also Be Reconciled
Reconciliation should not stop at GST, AIS and TDS.
The tax audit report and ITR should also tell the same financial story.
For example, taxpayers should review whether the following are consistent:
- Turnover
- Gross receipts
- Business income
- Professional receipts
- Expenses
- Depreciation
- Tax deductions
- Tax disallowances
- Brought-forward losses
- Unabsorbed depreciation
- TDS/TCS
- Other tax adjustments
- Closing balances where relevant
A difference between accounting profit and taxable income is not necessarily an error.
Accounting profit may need to be adjusted for items that are treated differently under income-tax provisions.
For example, tax computation may involve adjustments relating to:
- TDS non-compliance
- Certain cash payments
- Delayed payment of statutory dues
- Payments covered by applicable MSME-related provisions
- Depreciation differences
- Expenses not allowable under the Income-tax Act
- Other tax-specific adjustments
The key is that these adjustments should be correctly identified and consistently reflected in the relevant tax filings.
Books vs GST vs AIS vs 26AS vs ITR: A Simple Reconciliation Checklist
Before finalising the tax audit and ITR, taxpayers can use the following checklist.
| Reconciliation | What to Check |
|---|---|
| Books vs GST returns | Turnover, credit notes, debit notes, advances and other differences |
| Books vs AIS | Interest, dividends, securities and other reported transactions |
| Books vs TIS | Income and transaction information summarised in TIS |
| Books vs Form 26AS | TDS/TCS and other tax-credit information |
| TDS certificates vs 26AS | Deductor, PAN, amount and relevant financial year |
| GST vs ITR | Turnover and applicable adjustments |
| Tax audit report vs ITR | Income, deductions, losses and tax adjustments |
| Bank statements vs books | Receipts, payments and unidentified transactions |
The purpose is not to make every number identical.
The purpose is to ensure that every material difference has a reasonable explanation and supporting documentation.
What Taxpayers Should Do Before the September 30 Tax Audit Deadline
With the September 30, 2026 deadline approaching, taxpayers should complete the reconciliation process as early as possible.
Step 1: Finalise the books
Make sure sales, purchases, expenses, bank entries, receivables, payables and other accounting records are updated.
Step 2: Reconcile GST returns
Compare the books with applicable GST returns and investigate significant differences.
Step 3: Download and review AIS and TIS
Check reported interest, dividends, securities transactions, receipts and other information.
Step 4: Check Form 26AS
Verify TDS, TCS and other tax-payment information.
Step 5: Reconcile TDS certificates
Compare Form 16, Form 16A and other relevant certificates with Form 26AS and AIS.
Step 6: Investigate mismatches
Do not automatically change the books or ITR simply because another statement contains a different number.
First determine the reason for the difference.
Step 7: Correct reporting errors
Where the reporting entity has made an error, request correction from the relevant deductor, collector, bank, broker or other reporting entity.
Step 8: Review the tax audit report
Check Form 3CA/3CB and Form 3CD information against the financial statements and tax computation.
Step 9: Reconcile the ITR
Ensure that the final ITR reflects the correct income, deductions, tax adjustments, losses and tax credits.
Step 10: Keep an audit trail
Maintain reconciliation statements and supporting documents explaining material differences.
This documentation can be particularly useful if the taxpayer later needs to explain a mismatch or respond to a tax communication.
A Practical Example of AIS, GST and TDS Reconciliation
Consider a small business that has the following records:
- Turnover according to books: ₹1.20 crore
- Turnover reported through GST records: ₹1.18 crore
- Interest appearing in AIS: ₹80,000
- Interest recorded in books: ₹78,000
- TDS according to the taxpayer’s certificate: ₹35,000
- TDS reflected in Form 26AS: ₹30,000
At first glance, all four figures appear inconsistent.
But that does not automatically mean that the taxpayer has made an incorrect ITR filing.
The taxpayer should investigate each difference separately.
For the ₹2 lakh GST difference, the taxpayer should identify whether it relates to credit notes, exempt/non-GST transactions, advances, timing differences or another legitimate adjustment.
For the ₹2,000 interest difference, the taxpayer should check the bank statement and determine whether the AIS figure represents a different reporting period, a gross amount or an incorrect report.
For the ₹5,000 TDS difference, the taxpayer should check the TDS certificate and Form 26AS and contact the deductor if the amount has been reported incorrectly.
Only after completing these reconciliations should the final tax position be determined.
Do Not Blindly Match Every Number
One important point should be kept in mind:
Reconciliation does not mean forced matching.
A taxpayer should not change a genuine book entry merely because the figure in AIS or GST is different.
Similarly, a taxpayer should not automatically include an AIS transaction as taxable income without understanding its nature.
The correct approach is:
Identify → Verify → Reconcile → Correct if necessary → Document → Report correctly
This approach is more useful than simply trying to make every statement show the same number.
What If a Mismatch Remains After Filing the ITR?
If a tax-credit mismatch appears after filing, taxpayers should examine the reason and use the appropriate correction mechanism.
The Income Tax Department provides a Tax Credit Mismatch service where taxpayers can view differences involving TDS, TCS and tax payments.
Depending on the situation, correction may require action by the deductor or collector, filing a revised return where permitted, or using the appropriate rectification process after processing of the return.
The Income Tax Department also states that tax-credit mismatch correction can be used for correcting certain TDS/TCS/challan details in a processed return, subject to the applicable conditions.
Therefore, taxpayers should retain all supporting documents rather than relying only on screenshots or downloaded statements.
Final Checklist Before Tax Audit Deadline September 30
Before the tax audit report is finalised, check these five areas:
1. Books
Are sales, expenses, bank transactions and other accounting records complete?
2. GST
Does the GST turnover reconcile with the books, with documented reasons for differences?
3. AIS/TIS
Have all major transactions been reviewed and matched with source documents?
4. TDS/26AS
Have all TDS and TCS credits been verified?
5. ITR and Tax Audit Report
Are income, deductions, disallowances, losses and tax credits consistent?
The Income Tax Department itself has issued reminders that AY 2026-27 tax audit reports in Form 3CA-3CD/3CB-3CD are due by 30 September 2026.
Please Listen.
— Sanju⚜️ (@sxnjz___) September 21, 2026
Gujrat High Court To CBDT
Why Citizens Put Under Pressure and Stress when Your Portal Having Technical Glitches, and Why You Extend TAR Due Date in Last Rush..#Extend_Due_Date_Immediately #extend_ITR_TAR_duedates #ExtendTAXAUDITDUEDATE #GujaratHighCourt pic.twitter.com/89iVMLuS5g
Conclusion
The September 30 tax audit deadline should not be viewed merely as the final date for submitting the audit report.
For taxpayers subject to audit, the more important exercise is the reconciliation that happens before filing.
GST returns, books of account, AIS, TIS, Form 26AS, TDS certificates, financial statements, tax audit reports and ITRs are different sources of information. They can contain legitimate differences because of timing, reporting mechanisms and accounting treatment.
At the same time, unexplained differences should not be ignored.
Before finalising the tax audit and ITR, taxpayers should identify the reason for every material mismatch, obtain corrections wherever required and maintain supporting documents.
The goal is not to make every number identical. The goal is to make sure that every reported number is correct, explainable and supported by records.
For complex cases involving substantial differences, taxpayers should consult their Chartered Accountant or tax professional before filing.
Disclaimer: EduTaxTuber provides content for general educational and informational purposes only. While we make reasonable efforts to keep the information accurate and updated, laws, regulations, market conditions, software features, and other information may change. Some content may be created or assisted by AI tools and may contain errors or omissions. Readers should verify important information with official sources or qualified professionals before making any tax, legal, financial, investment, business, or other decisions. EduTaxTuber does not guarantee the completeness or accuracy of the information and does not provide professional advice.