Summary
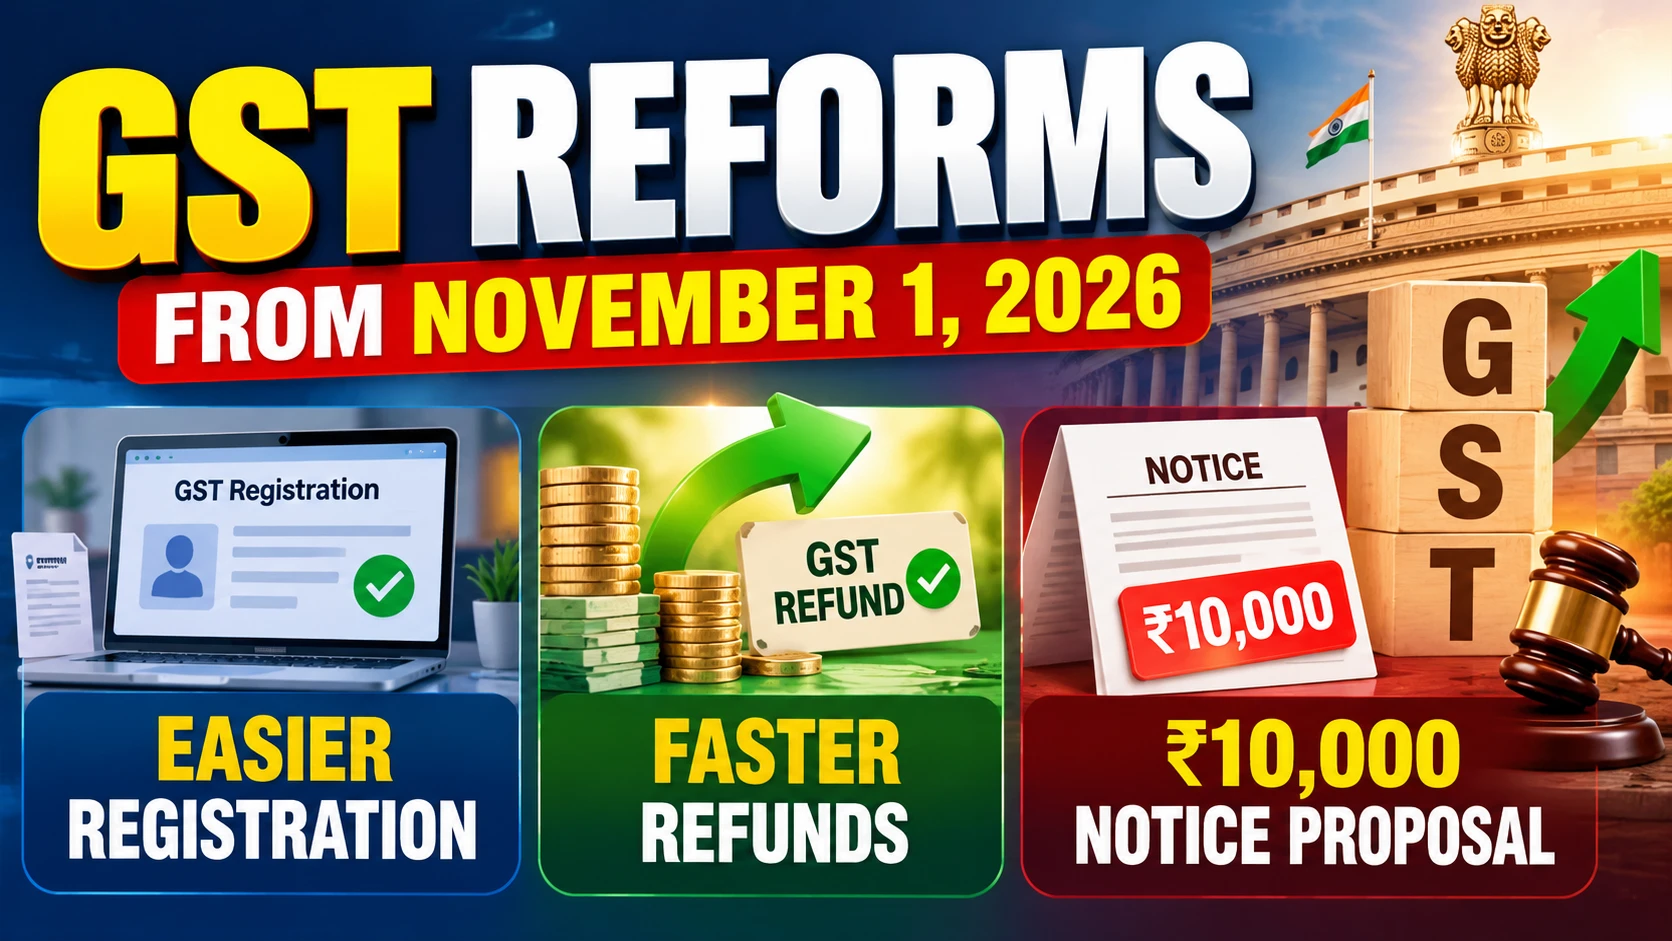
- GST process reforms are expected to be rolled out in phases beginning November 1, 2026.
- Small online sellers could get an easier way to obtain registrations in states where they do not maintain physical premises.
- The GST Council has recommended automated processing of specified refund claims.
- The proposed time limit for issuing refund acknowledgements or deficiency memos would fall from 15 days to 10 days.
- A ₹10,000 minimum tax-amount threshold for show-cause notices has been recommended, subject to the necessary legal changes.
- Implementation dates must be checked against official notifications and statutory amendments.
Why Is the Government Changing GST Procedures?
GST brought many indirect taxes under one nationwide system, but businesses still face practical problems with documentation, registration applications, refund delays and tax disputes.
A small seller may be able to reach customers across India through an online marketplace, yet registering in another state can require additional paperwork. Similarly, exporters and other eligible businesses can face working-capital difficulties when refund claims remain pending.
The 57th GST Council meeting, held on October 8, recommended several measures intended to reduce these difficulties.
The objective is to make compliance more predictable, reduce unnecessary departmental intervention and enable greater use of digital processes.
The latest development concerns the expected implementation schedule. Officials have indicated that changes requiring only administrative action may be introduced earlier than those needing amendments to the GST law.
Simplified GST Registration for Small E-Commerce Sellers
One of the most significant proposals concerns small businesses selling goods through e-commerce operators.
Under the recommended mechanism, eligible suppliers could obtain registration in a state or Union Territory where they do not have their own physical establishment by declaring an e-commerce operator’s warehouse as their principal place of business.
The Council recommended introducing Rule 14B in the CGST Rules, 2017, for this purpose.
This would be subject to prescribed conditions, including a limit on the amount of input tax credit the supplier intends to pass on.
What Does the ₹2.5 Lakh Limit Mean?
The proposal refers to sellers who intend to pass on input tax credit of not more than ₹2.5 lakh per month in the relevant circumstances, excluding stock transfers between distinct persons.
This is an ITC-related condition, not a monthly sales-turnover ceiling.
That distinction is important. Businesses should not interpret the figure as permission to sell only ₹2.5 lakh worth of products every month.
For example, a seller operating from Uttar Pradesh who uses an e-commerce company’s warehouse in another state may be able to benefit from the proposed mechanism, provided the final rules and eligibility conditions are satisfied.
This could reduce the need for separate physical premises in every state where inventory is stored.
Will GST Registration Be Completely Automatic?
The Council recommended a system-based registration mechanism subject to conditions.
That does not mean every online seller will qualify or that routine verification and legal obligations disappear.
Businesses will still need accurate documentation and must comply with applicable registration, reporting and tax-payment provisions.
The government has also proposed clearer documentation guidelines and improvements to Form GST REG-01 to reduce unnecessary queries and application rejections.
Faster GST Refunds: What Could Change?
Refund processing is another major focus of the proposed reforms.
Businesses can have money tied up in their electronic cash ledgers or accumulated input tax credit. Delays in receiving legitimate refunds can affect day-to-day operations, especially for exporters and smaller companies.
The GST Council recommended phased automation of specified refunds.
Automatic Refund of Excess Cash Ledger Balance
Under the recommended first phase, eligible refunds of excess balances held in the electronic cash ledger would be sanctioned automatically through the system.
The objective is to reduce the need for manual approval in straightforward cases.
However, taxpayers should wait for the operative notification and portal implementation before treating this process as available.
Acknowledgement Timeline Could Reduce to 10 Days
The Council also recommended reducing the deadline for issuing a refund acknowledgement or deficiency memo from 15 days to 10 days.
If the prescribed response is not issued within the proposed period, the system would generate a deemed acknowledgement under the contemplated procedure.
This could help applicants establish the status of their refund claims sooner.
It is important to distinguish acknowledgement from final payment. Acknowledgement does not itself mean that the entire refund has been sanctioned.
Read Also: Jio Platforms IPO 2026: ₹2.5 Lakh Crore Anchor Demand Reported Ahead of October 21 Opening
Provisional Refunds Up to 90%
For specified claims relating to zero-rated supplies and the inverted duty structure, the Council recommended system-based provisional sanction of 90% of the claimed amount.
Such processing would remain subject to risk identification and evaluation.
For exporters, this could provide earlier access to funds that would otherwise remain blocked while applications are examined.
The final sanction, adjustment and recovery provisions will continue to depend on applicable law.
₹10,000 Threshold for GST Notices: What Does It Mean?
Another important proposal concerns smaller tax disputes.
The Council recommended introducing a minimum tax-amount threshold of ₹10,000 for issuing show-cause notices under the relevant provisions.
The recommended threshold concerns the combined amount of CGST, SGST, IGST and cess.
This should not be confused with a blanket waiver of all GST liabilities below ₹10,000.
Nor should taxpayers conclude that existing notices have automatically been cancelled.
The government would need to give legal effect to the proposal, including any transitional treatment of pending notices or appeals.
If implemented as recommended, the measure could reduce minor disputes and allow tax authorities to devote more resources to higher-value cases.
Which Changes May Start on November 1?
The expected rollout has attracted attention because different reform measures require different legal steps.
| Proposed measure | Reported implementation position |
|---|---|
| Registration documentation simplification | Early phased implementation expected |
| Simplified registration for eligible online sellers | Proposed; operative rules awaited |
| Automated refund processing | Phased rollout expected |
| Refund acknowledgement within 10 days | Subject to procedural implementation |
| ₹10,000 GST notice threshold | Requires appropriate legal changes |
| Selected wider ITC refund eligibility | Separate effective-date provisions apply |
The Economic Times reported on October 22 that changes requiring administrative action are expected to begin from November 1, 2026, whereas legislative changes are expected from April 1, 2027.
These dates describe the reported implementation plan. They do not establish that each measure is already legally operative.
Businesses should check the relevant notifications, circulars and GST portal advisories before changing their procedures.
How Will Small Businesses Benefit?
Consider a small online retailer that sells products through a major marketplace.
At present, the business may face difficulties meeting documentation requirements when its goods are stored in warehouses across states.
A properly implemented simplified registration mechanism could make it easier to operate through an e-commerce warehouse without maintaining separate physical premises.
Likewise, quicker refund processing could help a manufacturer or exporter recover eligible funds sooner.
For smaller businesses, this matters because cash flow is often more important than the amount of profit shown in financial statements.
When money remains blocked in taxes or refunds, businesses may have to borrow more or delay payments to suppliers.
Reducing avoidable administrative delays can therefore produce financial benefits even without changing GST rates.
What Should GST-Registered Businesses Do Now?
Businesses should use the period before implementation to review their compliance records.
E-commerce sellers should identify the states where inventory is stored and understand whether they could satisfy the proposed Rule 14B conditions.
Exporters and other refund applicants should reconcile electronic ledgers, invoices, returns and supporting documents.
Businesses dealing with GST notices should continue to meet existing statutory deadlines.
A proposal to introduce a ₹10,000 threshold is not a reason to ignore notices already received.
Tax professionals should monitor the CBIC and GST portal for the final legal instruments and practical implementation instructions.
More Stories

India October PMI 2026: Business Growth Hits 4-Month High, but Hiring Slows
GST Reforms From November 1, 2026: Easier Registration, Faster Refunds and ₹10,000 Notice Proposal
HPCL Q2 Results 2026: ₹3,625 Crore Profit After Q1 Loss, but Half-Year Remains in Red
Adani Energy Q2 Results 2026: Profit Jumps 145% to ₹1,364 Crore, Smart Meter Business Expands
Are These Reforms Different From GST Rate Cuts?
Yes. This reform package primarily concerns tax administration rather than a fresh across-the-board reduction in GST rates.
The proposed changes deal with how taxpayers register, receive refunds and respond to proceedings.
GST rates applicable to goods and services must be determined from the relevant notified rate schedules.
Businesses should therefore avoid announcing changes to customer prices merely because procedural GST reforms are expected.
What Happens Next?
The key development to monitor is the issuance of the relevant notifications, circulars and law amendments.
The government is expected to implement the reforms in stages, giving businesses and the GST portal time to accommodate the revised procedures.
The final rules will determine exactly who qualifies, what documents are required and when each new process becomes available.
For now, the direction is clear: the GST administration is moving towards simpler documentation, increased automation and reduced procedural friction.
The practical benefits, however, will depend on how effectively those recommendations are implemented.
Frequently Asked Questions
1. Will new GST registration rules apply from November 1, 2026?
Officials have indicated that certain administrative reforms are expected to begin from November 1. The applicable notification must be checked to confirm the commencement date of each measure.
2. Can small sellers use an e-commerce warehouse as their business address?
The GST Council has recommended a mechanism allowing eligible suppliers to declare an e-commerce operator’s warehouse as their principal place of business in specified circumstances.
3. Are all GST refunds becoming automatic?
No. The proposals cover specified refund categories and contemplate phased implementation with risk-based checks.
4. Will GST notices below ₹10,000 be cancelled?
Not automatically. The Council has recommended a minimum threshold, but the applicable legal amendments and transitional provisions determine its operation.
5. Is ₹2.5 lakh the turnover limit for the proposed seller scheme?
No. The amount refers to the input tax credit intended to be passed on per month under the proposed eligibility framework, not directly to monthly sales turnover.
6. Where can businesses check the final GST changes?
Businesses should consult CBIC notifications, the official GST portal and government releases for effective dates and operative instructions.
Related Reading on EduTaxTuber
Sources
- Ministry of Finance, PIB: Recommendations of the 57th GST Council Meeting, 8 October 2026.
- PIB: Next-Gen GST Process Reforms, 9 October 2026.
- The Economic Times: GST reforms from November 1, 22 October 2026.
- Official GST portal: https://www.gst.gov.in/
Disclaimer
This article is prepared for general educational and informational purposes with AI assistance and editorial source review. Although reasonable care has been taken to explain the reported developments accurately, readers should verify current notifications, circulars and applicable statutory provisions before acting. EduTaxTuber does not provide personalised tax, legal or financial advice and accepts no responsibility for losses arising from reliance on this article, subject to applicable Indian law, including the Information Technology Act, 2000. No disclaimer excludes liability that cannot lawfully be excluded.
Disclaimer: EduTaxTuber provides content for general educational and informational purposes only. While we make reasonable efforts to keep the information accurate and updated, laws, regulations, market conditions, software features, and other information may change. Some content may be created or assisted by AI tools and may contain errors or omissions. Readers should verify important information with official sources or qualified professionals before making any tax, legal, financial, investment, business, or other decisions. EduTaxTuber does not guarantee the completeness or accuracy of the information and does not provide professional advice.
