

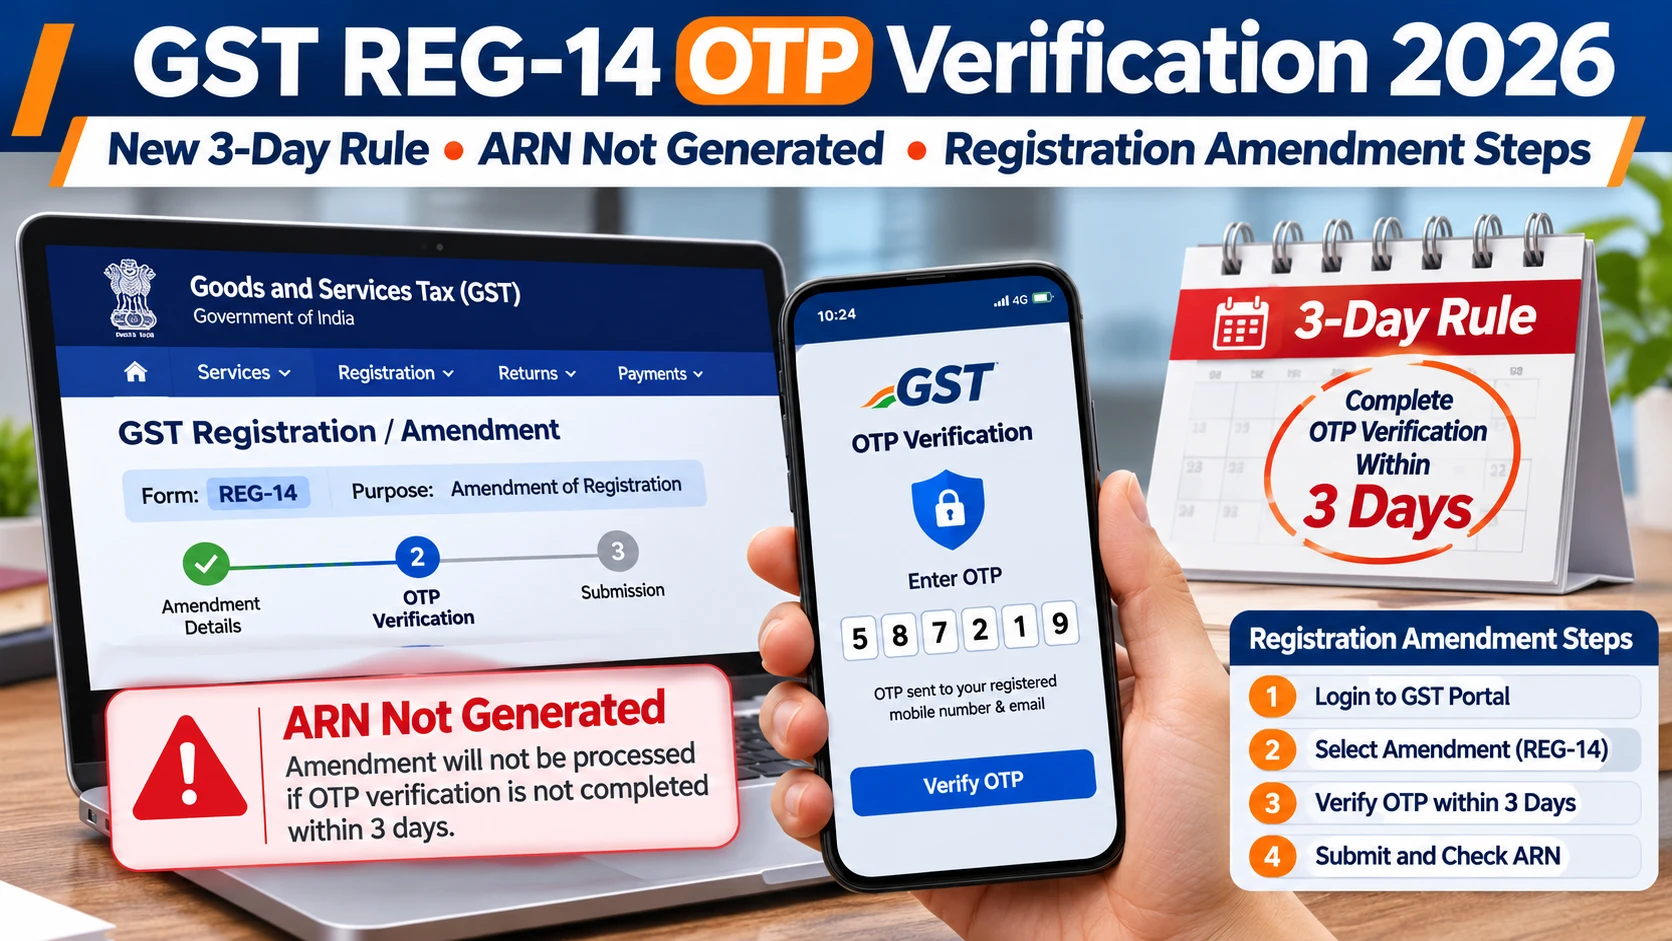
Businesses changing the particulars of an existing GST registration must now pay closer attention to online verification requirements.
The Goods and Services Tax Network (GSTN) issued Advisory No. 686 on 1 November 2026, confirming that revised registration-amendment procedures have been implemented on the GST portal.
Summary
- GSTN issued Advisory 686 on 1 November 2026.
- The corresponding portal changes are already implemented.
- The revised procedure concerns amendments to existing GST registration particulars.
- FORM GST REG-14 is the relevant amendment application.
- Mandatory mobile-number and email OTP verification must be completed within three days.
- Verification involves the primary authorised signatory and one selected prescribed business representative.
- PAN, DIN and CIN validations may also apply.
- Without successful prescribed verification, an ARN will not be generated.
- Amendments to the principal place of business continue to be examined by the proper officer.
- The advisory does not introduce a GST rate increase.
What Has Changed in GST Registration Amendments?
Notification No. 05/2026–Central Tax, dated 26 October 2026, introduced changes to the registration-amendment framework under the Central Goods and Services Tax Rules.
GSTN subsequently updated the common portal to reflect the revised procedures.
The changes are intended to improve online validation and streamline processing of eligible amendments.
For many registration particulars other than the principal place of business, the amended registration certificate can be generated following successful submission and prescribed online validations.
However, the new process introduces an important verification requirement.
Taxpayers must ensure that the designated persons can complete the necessary OTP checks within the stipulated period.
GST REG-14: What Is This Form?
FORM GST REG-14 is used by registered taxpayers to apply for permitted amendments to their existing registration particulars.
It is different from FORM GST REG-01, which is generally used for new GST registration applications.
For example, a company applying for its first GSTIN may need REG-01.
A company that already has a GSTIN but needs to amend relevant information generally uses the appropriate registration-amendment process through REG-14.
Confusing these two forms can lead taxpayers to follow the wrong instructions.
Which Registration Changes Are Covered?
GSTN’s advisory discusses changes involving particulars such as the legal name of the business, addition or removal of relevant business persons and additional places of business.
The precise procedure depends on the field being amended and the applicable legal requirements.
Changes to the Principal Place of Business
Changes relating to the Principal Place of Business (PPOB) continue to be examined by the proper officer.
A business changing its main registered address should therefore not assume that submission and OTP validation alone guarantee approval.
The relevant documents and the proper officer’s examination remain important.
Other Registration Particulars
For eligible changes other than PPOB amendments, the revised framework permits amendment of the registration certificate upon submission and successful prescribed online validations.
This may include certain changes involving directors, partners, other specified persons and additional places of business.
However, taxpayers must continue to supply accurate information and required supporting documents.
What Is the New Three-Day OTP Rule?
The amended process requires online verification of the mobile number and email address associated with designated persons.
The required persons include:
- The Primary Authorised Signatory.
- One selected Promoter, Partner, Director, Karta, Member, Trustee or other applicable person.
GSTN allows three days from the date of submission of the amendment application to complete this verification.
This is a verification period, not a blanket promise that all GST registration amendments will be approved within three days.
What Happens if OTP Verification Is Not Completed?
GSTN expressly states that the ARN will not be generated when mandatory verification is not completed within the prescribed three-day period.
An ARN is important because it identifies an application submitted through the GST system.
Without it, taxpayers may encounter difficulties treating the amendment as properly completed or tracking its progress.
Businesses should not assume that entering new details in the portal means the amendment process is finished.
They should verify both successful submission and the generation of the required reference number.
How to Complete GST OTP Verification
The official advisory identifies a dedicated GST portal facility.
Step 1: Prepare Your Amendment Application
Log in to the GST portal and access the relevant registration-amendment facility.
Enter the required information in FORM GST REG-14 and upload the necessary documents.
Step 2: Check the Registered Contact Details
Before completing the process, confirm that the designated persons have access to the mobile numbers and email addresses required for verification.
Incorrect or inaccessible contact details can create delays.
Step 3: Open the OTP Verification Facility
Navigate to:
Services → Registration → OTP Verification of GSTIN
The official verification facility is also available at:
https://services.gst.gov.in/services/otpVerification
Step 4: Complete the Prescribed Verification
Follow the portal instructions to verify the mobile numbers and email addresses of the required persons.
Do not share OTPs with unauthorised individuals.
Step 5: Complete Verification Within Three Days
The prescribed verification must be completed within three days from submission.
Businesses should avoid delaying until the final day.
Step 6: Check ARN Generation
After successful completion of the necessary validations, check whether the portal generates the ARN.
Retain the ARN and the relevant acknowledgement for future reference.
Step 7: Download the Amended Certificate
Where applicable, the amended registration certificate becomes available on the GST portal following successful completion of the prescribed process.
The steps above summarise GSTN’s published workflow. Actual screens and additional requirements may vary according to the amendment type.
GST ARN Not Generated: What Should You Check?
If an amendment application does not produce an ARN, businesses should investigate the applicable validation requirements.
1. Has OTP Verification Been Completed?
Check the prescribed verification status for the primary authorised signatory and the other selected person.
2. Are the Registered Mobile Number and Email Accessible?
An outdated contact number or an inaccessible email account may prevent timely verification.
3. Is There an Identification Mismatch?
The portal also validates relevant identification information, including PAN, DIN and CIN where applicable.
Businesses should confirm that the information matches their relevant official records.
4. Was the Three-Day Period Missed?
Check the submission date and the status of verification.
If the permitted period has elapsed, follow current GSTN support instructions to determine the next valid action.
Do not assume that a new ARN will automatically be generated after a missed deadline.
5. Is the Amendment Subject to Officer Examination?
Changes to the principal place of business remain subject to examination by the proper officer.
Such applications should not be assessed as though every amendment follows an identical automated process.
More Stories

ChatGPT in Excel: 5 Powerful AI Tricks to Save Time (Hindi Tutorial)
GST REG-14 OTP Verification 2026: New 3-Day Rule, ARN Not Generated and Registration Amendment Steps
SEBI NRI KYC Rules 2026: Open Investment Accounts From Abroad Without Visiting India — 7 Major Changes
GST Rule 14B Registration 2026: How Online Sellers Can Register in Another State Without Their Own Office
Does the New Process Apply to OPCs?
A One Person Company registered under GST must follow the amendment requirements applicable to its legal constitution and registration particulars.
The revised registration framework separately recognises OPCs in new-registration FORM GST REG-01.
However, the current advisory concerns existing registration amendments through REG-14.
An OPC should therefore distinguish between applying for a new GSTIN and changing information in an existing GST registration.
Where verification of a director or another prescribed person is required, the relevant identification and contact information should be checked carefully.
PAN, DIN and CIN Validation
GSTN has also specified online validation of identification particulars, where applicable.
These include:
- Permanent Account Number (PAN).
- Director Identification Number (DIN).
- Corporate Identification Number (CIN).
The required validations must succeed before the ARN can be generated under the applicable process.
A company changing director-related details should therefore check the accuracy of relevant corporate records before submitting its amendment.
This can reduce the likelihood of preventable mismatches.
Example: A Company Adds a New Director
Suppose an existing registered company needs to update its GST registration after a change involving a director.
The company identifies the applicable registration-amendment field and submits the required information through the portal.
The relevant PAN, DIN or CIN information may undergo online validation.
The designated persons must then complete the prescribed mobile and email OTP verification.
If the required verification succeeds, the application can progress under the applicable revised process.
If verification is incomplete, the ARN will not be generated as specified by GSTN.
The example is illustrative. Actual requirements depend on the facts and the relevant portal workflow.
Example: A Business Changes Its Main Office Address
Now consider a business shifting its principal registered office from one location to another within the state.
This is a change involving the principal place of business.
GSTN has expressly retained proper-officer examination for this category.
Therefore, the business should prepare the prescribed address documents and follow the applicable examination and approval process.
It should not assume the same automated treatment available for other eligible amendments.
What Should GST Practitioners and Accountants Do?
Tax professionals managing registration amendments for clients should update their internal checklists.
Before submitting an amendment, confirm the nature of the change and the required supporting documents.
Also verify which persons must complete OTP authentication.
The primary authorised signatory and the selected business representative should be informed of the verification requirement before the application is submitted.
This is especially important where the client, director and accounting professional are in different locations.
Businesses should maintain records of successful verification and the final ARN.
How Is This Different From GST Rule 14B?
Rule 14B concerns a separate registration facility for eligible e-commerce goods sellers using a qualifying operator’s warehouse in another state.
The current REG-14 advisory concerns amendments to existing GST registration particulars.
Read Also: GST Rule 14B warehouse-registration process
Although both involve GST registration procedures, they address different problems.
Businesses should select the procedure relevant to the action they actually need to perform.
Frequently Asked Questions
1. What is the new GST REG-14 OTP rule?
GSTN requires prescribed mobile and email OTP verification within three days for applicable registration amendments.
2. When was the advisory issued?
1 November 2026.
3. Which GST form is used for registration amendments?
FORM GST REG-14.
4. How long is the OTP verification period?
Three days from submission of the amendment application.
5. What happens if OTP verification is incomplete?
The ARN will not be generated where the mandatory verification is not completed within the specified period.
6. Will changing the main office address be automatically approved?
Not merely through the revised online-validation procedure. Principal place-of-business amendments continue to be examined by the proper officer.
7. What information is validated online?
PAN, DIN and CIN, wherever applicable, along with the required mobile and email verification.
8. Does this introduce a new GST rate?
No. These are registration-amendment procedures.
Conclusion
GSTN’s November 2026 amendments introduce an important new operational requirement for businesses updating their existing GST registrations.
The three-day OTP verification deadline is especially significant because incomplete verification can prevent ARN generation.
Taxpayers should distinguish amendments requiring officer examination from other eligible changes processed through the revised online-validation system.
Preparing accurate documents and ensuring timely verification can help avoid unnecessary delays.
Sources
- GSTN Advisory No. 686, dated 1 November 2026.
- Notification No. 05/2026–Central Tax, dated 26 October 2026.
- GST Portal — OTP Verification of GSTIN facility.
Disclaimer: EduTaxTuber provides content for general educational and informational purposes only. While we make reasonable efforts to keep the information accurate and updated, laws, regulations, market conditions, software features, and other information may change. Some content may be created or assisted by AI tools and may contain errors or omissions. Readers should verify important information with official sources or qualified professionals before making any tax, legal, financial, investment, business, or other decisions. EduTaxTuber does not guarantee the completeness or accuracy of the information and does not provide professional advice.
